What a fantastic six months it’s been for Baldwin Insurance Group. Shares of the company have skyrocketed 44.2%, hitting $31.86. This performance may have investors wondering how to approach the situation.
Is now the time to buy Baldwin Insurance Group, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Baldwin Insurance Group Not Exciting?
We’re glad investors have benefited from the price increase, but we’re sitting this one out for now. Here are three reasons why there are better opportunities than BWIN, plus one stock we’d rather own.
1. Shrinking Adjusted Operating Margin
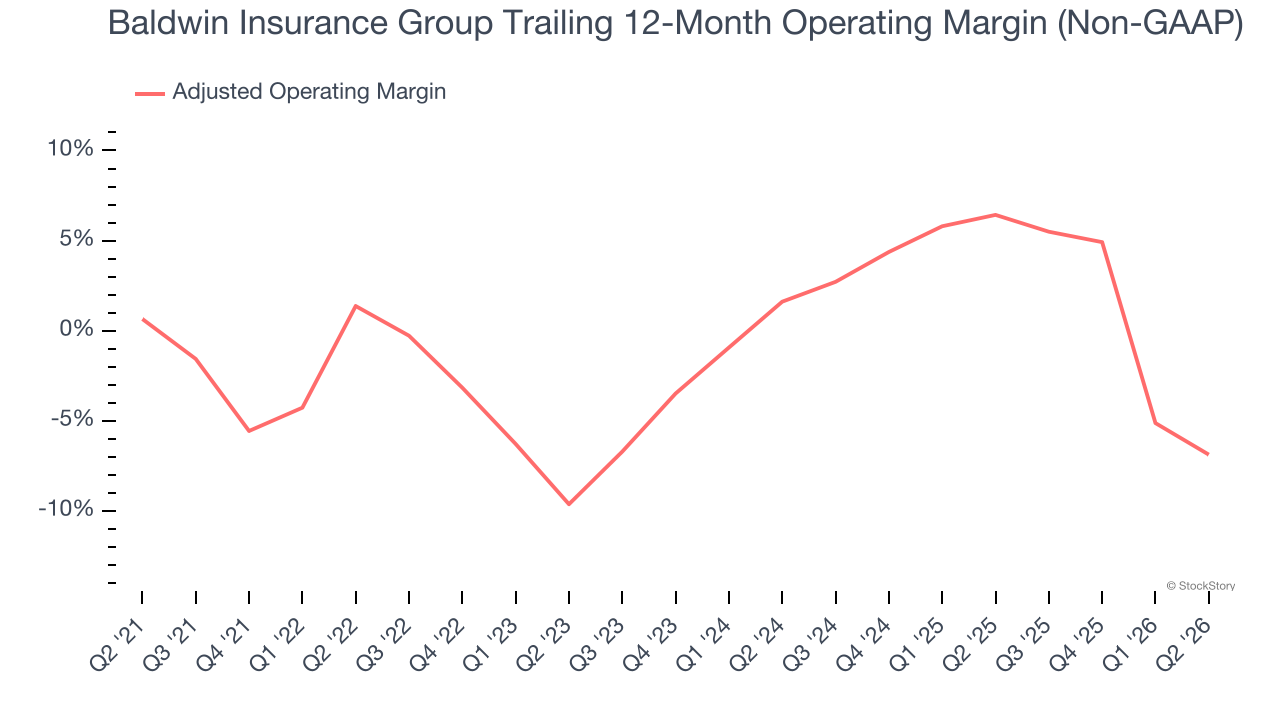
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt, and taxes.
Analyzing the trend in its profitability, Baldwin Insurance Group’s adjusted operating margin decreased by 8.2 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Baldwin Insurance Group’s performance was poor no matter how you look at it - it shows that costs were rising and it couldn’t pass them onto its customers. Its adjusted operating margin for the trailing 12 months was negative 6.9%.
2. Cash Burn Ignites Concerns
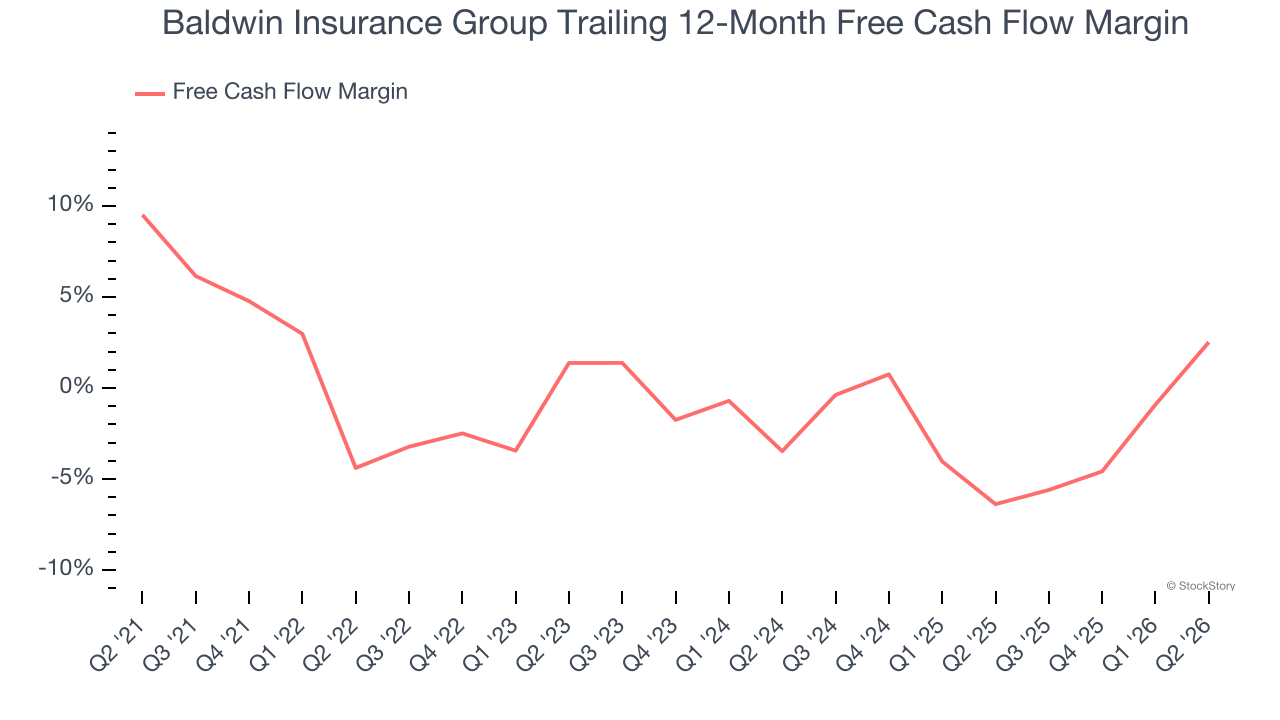
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
While Baldwin Insurance Group posted positive free cash flow this quarter, the broader story hasn’t been so clean. Baldwin Insurance Group’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 1.8%, meaning it lit $1.77 of cash on fire for every $100 in revenue.
3. High Debt Levels Increase Risk
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Baldwin Insurance Group’s $2.85 billion of debt exceeds the $610.7 million of cash on its balance sheet. Furthermore, its 6× net-debt-to-EBITDA ratio (based on its EBITDA of $396.2 million over the last 12 months) shows the company is overleveraged.
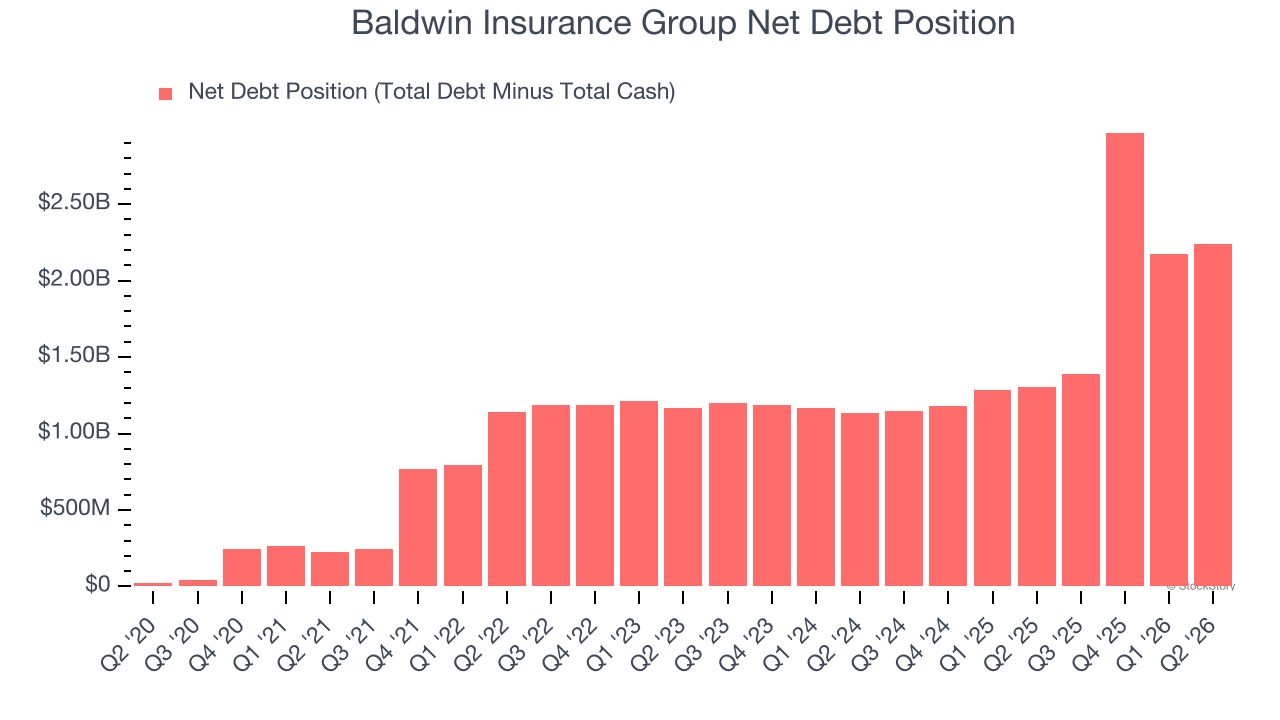
At this level of debt, incremental borrowing becomes increasingly expensive and credit agencies could downgrade the company’s rating if profitability falls. Baldwin Insurance Group could also be backed into a corner if the market turns unexpectedly – a situation we seek to avoid as investors in high-quality companies.
We hope Baldwin Insurance Group can improve its balance sheet and remain cautious until it increases its profitability or pays down its debt.
Final Judgment
Baldwin Insurance Group’s business quality ultimately falls short of our standards. After the recent rally, the stock trades at 14× forward P/E (or $31.86 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. We’d suggest looking at the most entrenched endpoint security platform on the market.
Stocks We Like More Than Baldwin Insurance Group
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.